
Excess crude and key product inventories are normal when allowing for seasonality and demand.
Gasoline and diesel supplied (consumption) look suspiciously low and product exports appear unusually high, but otherwise, the picture is as it has been on the consumption side, with refined product consumption running about 5% below normal.
Incentive-to-store analysis shows that market sentiment has been absolutely crazy over the last month and a half. On Sept. 27, the market perceived a huge crude supply deficit. This has reversed into the current modest surplus, per our analysis of the futures curve. This really should not happen, but clearly, it has.
US oil production remains flat at 13.2 mbpd, as it has been for the last eight weeks. I cannot find a similar eight week stretch in the data, which suggests that the EIA is winging it, as the EIA’s new software upgrades remain unreliable in reporting production.
The Brent Spread (Brent – WTI) has widened to $5 / barrel, which is normally consistent with US production growth of around 800 kbpd / year. US production growth is likely under-estimated, possibly materially so.
Overall, the EIA’s software upgrade remains buggy. The missing barrel count (red circle, the difference between the light and dark blue lines, graph above), instead of declining as the EIA had no doubt hoped (green circle), has exploded, and seemingly in a cumulative fashion. This is not unusual for software modifications, particularly in such rich, data-intensive and near-real-time systems as the EIA uses. It’s really the 8th wonder of the world, but the EIA will require a few weeks to iron out the kinks. Take the data with a grain of salt in the interim.
Urals weaker; Ruble stronger; UAE mischief; Danish grit
Russia Oil Prices
Brent has settled into the low $80s, closing on Wednesday at $82 / barrel. Urals tracked Brent with a few days' lag, closing at $65 mid-week. Urals is $9 / barrel above the 2015-2021 average and $5 above the Price Cap. This is good for Ukraine, as last week.
Oil demand depends upon the state of the global economy. The US economy is unwinding pandemic fiscal and monetary policy, and prices of a number of goods are falling, yet remain well above their pre-pandemic level. The question is therefore whether the US sees a 'soft landing' with the economy returning to pre-covid levels, or whether it overshoots into a recession. The price of oil will depend heavily on which version proves out. Moreover, China's economic prospects remain uncertain, and we might expect a financial crash there as the country transitions from a high growth to a lower growth regime. But when?
US shale production set the price of oil from mid-2014 until December 2021, and still remains a key constraint on oil price increases. The EIA has called peak US oil production for this past August, but statistical analysis suggests production growth may be higher than thought. The EIA has revised US production up by about 1 mbpd since the summer, and another material revision would come as no surprise. If US production is growing faster than believed, then oil prices could be quite a bit softer, at least for a few more months.
Thus, we have a fair amount of uncertainty on both the oil demand and supply side, none of which should influence appropriate policy regarding the Price Cap -- although reforming the Cap would be easier in a lower oil price environment.

As we forecast last week, the Urals Discount, the difference between the Urals and Brent oil prices, widened again this week, on Wednesday reaching $14.69 / barrel for the week as a whole. The ESPO discount also widened, but is now under $4 / barrel. China has agreed to work with the US on certain matters, and opening the ESPO discount wider should be on the table, as a discount of a measly $4 is less than the difference between Brent and WTI.

Ruble
The ruble continues to appreciate against the dollar, closing at 88.4 ruble / USD on Wednesday, likely buoyed by high oil prices during the last month or two. If Brent stays weak for any period of time, expect the ruble to slip back into the 90s.

The US Treasury sanctions UAE Mischief
The US Treasury sanctioned three UAE-based companies for shipping oil above the $60 / barrel cap. The Treasury details the penalties:
[All] property and interests in property of the [sanctioned] persons above that are in the United States ... are blocked, [as are] any entities that are owned ... by one or more blocked persons. These prohibitions include the making of any contribution or provision of funds, goods, or services by, to, or for the benefit of any blocked person and the receipt of any contribution or provision of funds, goods, or services from any such person.
The respective shipping companies are short-lived, special purpose vehicles chartering the tankers in question. It is fair to assume that these shell companies have no assets in the US and that the owners, if they can be identified at all, are either strawmen or have no interests in the US. The Treasury precludes these companies from using US suppliers. This principally matters for insurance, and that is primarily British. If British insurance is unavailable, these shipping companies can use Russian insurance. Thus, Treasury sanctions look largely toothless and symbolic. This is typical of prohibition enforcement.
The UAE is more broadly a hub for Price Cap evasion and serves as a case study of the black markets, corruption, and the antagonistic behavior which arises as a result of prohibitions. More on this in a separate post.
Danes show some Grit
The Financial Times reports that "Denmark would target tankers transiting the Danish straits without western insurance, under laws permitting states to check vessels they fear pose environmental threats." This must have come from the Danes themselves, and it is a welcome display of initiative and determination. Of course, the proposal was torpedoed as soon as it was launched, as black market theory predicts. Prohibitions attempt to prevent willing buyers from transacting with willing sellers, and the Danish initiative would prevent those willing buyers, indirectly the G7 countries, from acquiring needed oil. Therefore, the proposed interdiction never saw the light of day, as we would expect.
Nevertheless, this is very much the right idea. It cannot. however, be enforced in the form of a prohibition. Black market theory makes that plain enough. But there are better alternatives.
Rigs and Spreads Nov. 17: Rig and spread gains within overall steadiness
The breakeven to add US horizontal oil rigs now exceeds $90 / barrel WTI. That is, at $90 WTI, we can expect US operators to be cutting rigs. That is incredible by the standards of the last decade, when analysts like Goldman Sachs spoke of $30-40 breakevens.
Rig counts are essentially holding steady over the last five weeks
Total oil rig counts: +6 to 500
Horizontal oil rig counts: +6 to 452
The Permian horizontal oil rig count: +5, the biggest gain since February
The Canadian horizontal oil rig count eased back this week, -4 to 119, now 10 below this week last year
The US horizontal oil rig count is rising at a pace of +0.75 / week on a 4 wma basis.
This number is positive for the third time in the last 50 weeks
Frac spreads rose, +8 to 276
DUC inventory, as measured in days of turnover, fell to a new low of 12.8 weeks
Since July 2020, 16% of completions have come from cannibalization of DUC inventory
The Brent Spread (Brent – WTI) remains open, suggesting US shale oil production is exceeding expectations.
This is also true if we consider US production including unaccounted-for barrels, which continues to suggest production growth in the 600-800 kbpd / year pace
Ukraine Funding: The Price Cap and Illegal Immigration are the Same Problem
Russian Oil Prices
Brent continued to unravel last week, closing on Friday at $81. Accordingly, Urals has also fallen just below $70 for the first time in two months. A lower Urals price is good for Ukraine, although it remains well clear of the $60 Price Cap.

The Urals discount -- the difference between Brent and Russia's western crude oil export price -- narrowed to $10.00 / barrel last week, but this is likely an artefact of reporting disparities between Brent and Urals. Expect the discount to widen to $13.50 as Brent stabilizes.

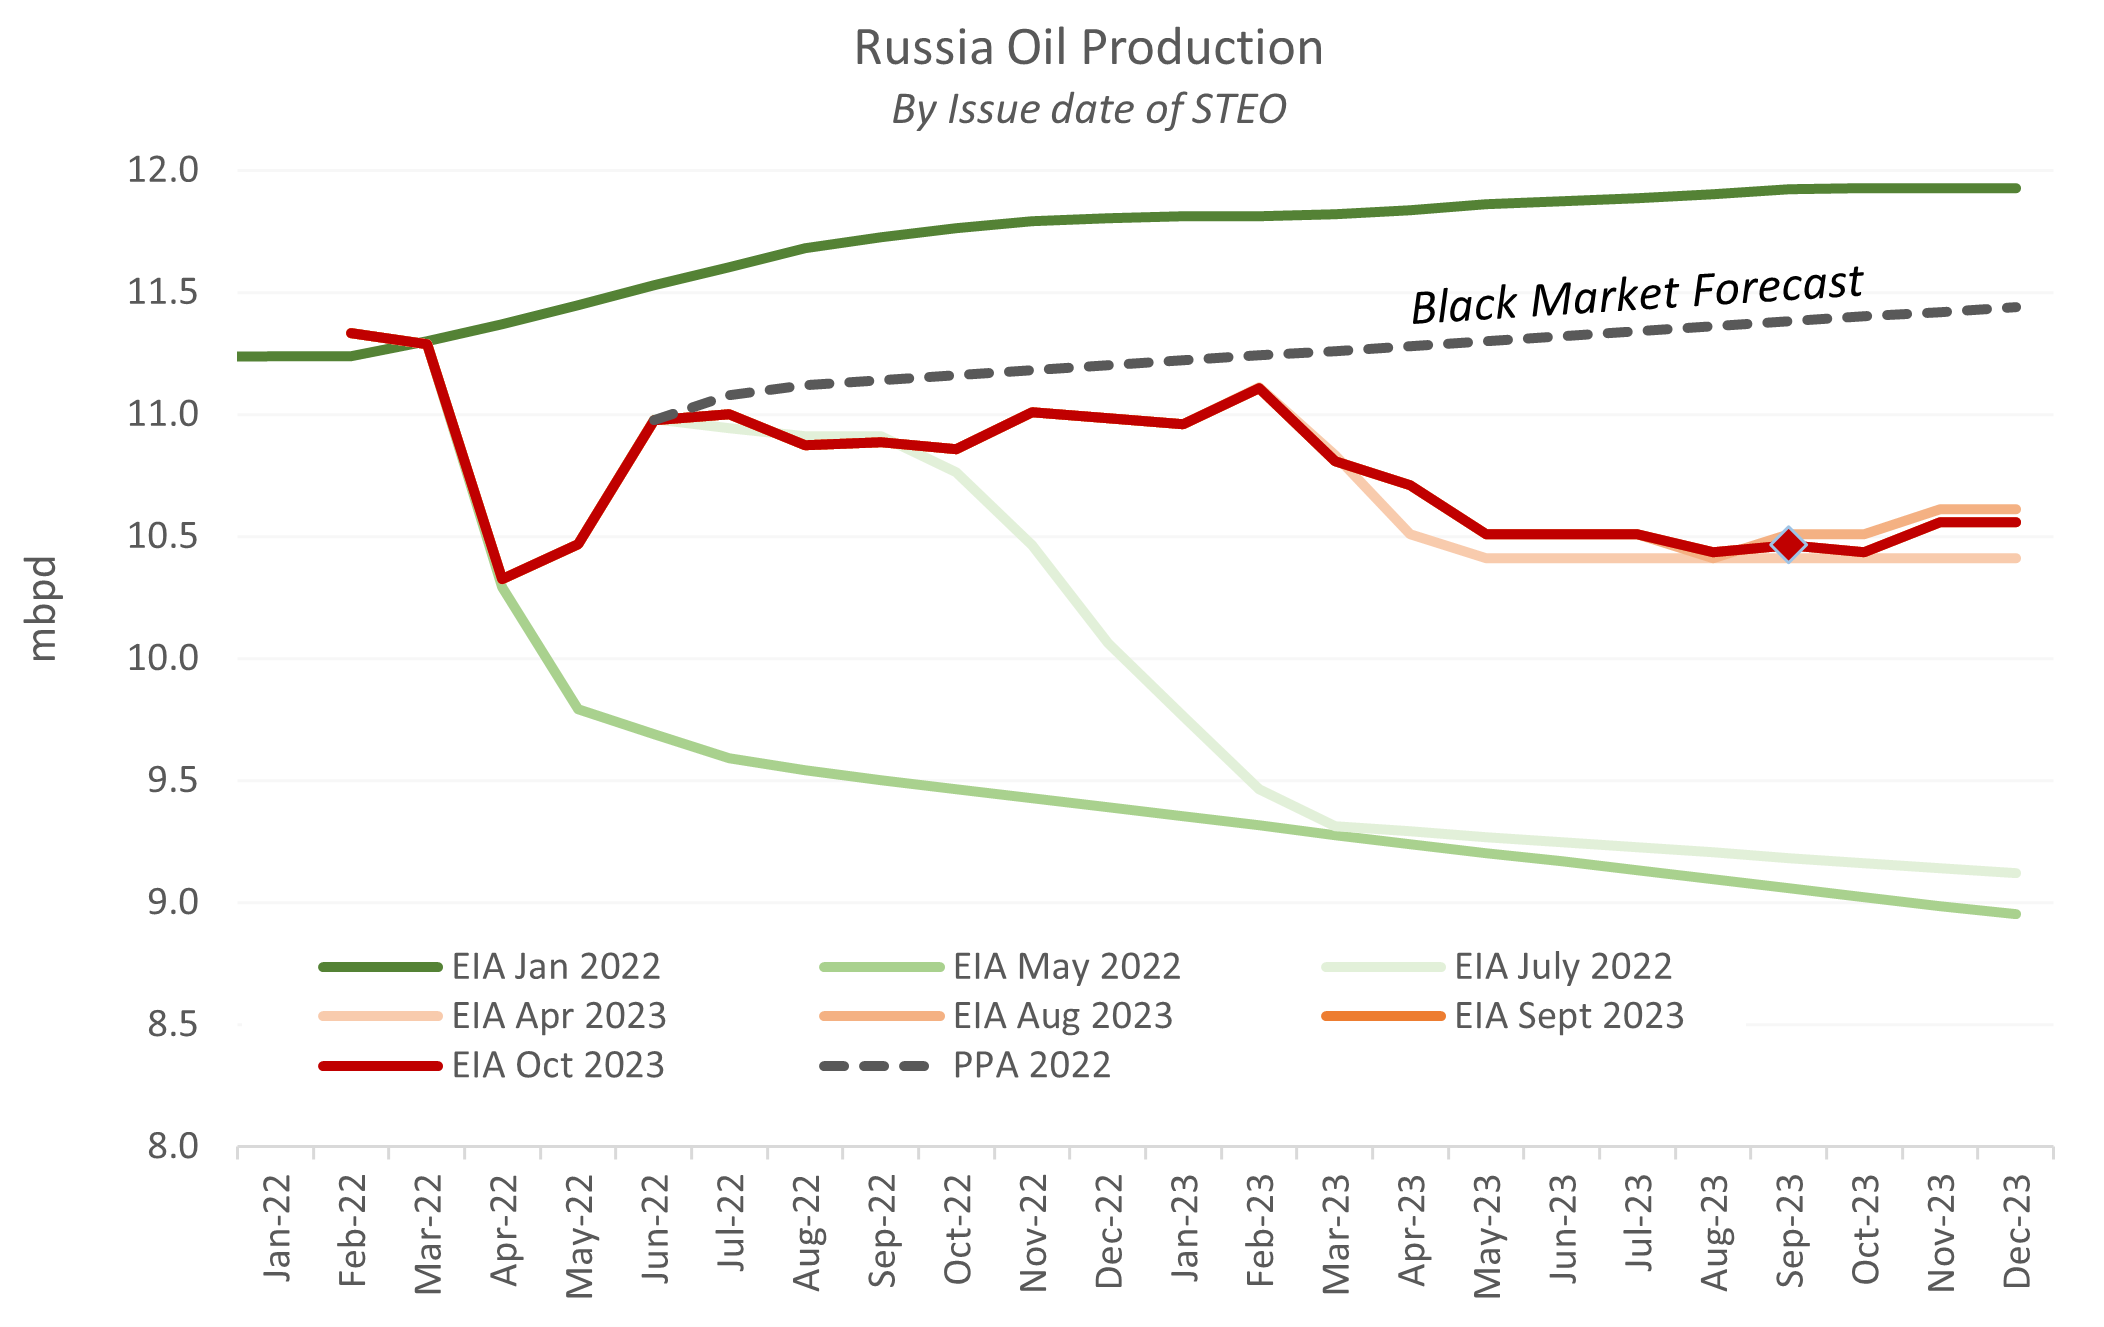
The EIA issued its November estimate of Russian oil production this past week. The Russian oil supply has been revised up 0.1 mbpd across the board starting in September 2022. Such revisions are not unusual for the EIA and are minimal considering uncertainties about Russian oil production during this wartime period. At 10.6 mbpd, Russia's October oil production was 7% below its pre-war output and 11% below the EIA's pre-war forecast for the month of October. As last month, the EIA expects no further reductions in Russian oil output, and indeed, sees Russian supply increasing by 0.15 mbpd (+1.4%) heading into 2024.

The Price Cap and Illegal Immigration
The new Speaker of the House, Mike Johnson (R, La), finds himself in a precarious situation. On Saturday, he unveiled a proposal to avoid a partial government shutdown by extending government funding for various programs until Jan. 19 and Feb. 2, according to the Associated Press. The bill excludes the funding for Israel and Ukraine which the Biden administration has requested. Johnson defended the bill as placing the "conference in the best position to fight for fiscal responsibility, oversight over Ukraine aid, and meaningful policy changes at our Southern border.”
Thus, funding for Ukraine has become intertwined with illegal immigration. Since evading the Price Cap and illegal immigration are the same problem in economic terms -- both are black markets -- they can be addressed with similar approaches.
Black markets arise as a result of prohibitions. A prohibition occurs when a government attempts to prevent willing buyers from transacting with willing sellers at market prices. Illegal immigration exists because the demand for US work visas is vastly greater than the supply of those visas at the offered price of $190. Therefore, unskilled labor from Latin America and elsewhere has an incentive to jump the US border, knowing that willing buyers -- US businesses -- are waiting to purchase the migrants' labor at 4-7x the wages of their home countries. That's illegal immigration in a nutshell.
The Embargo and Price Cap on Russian oil are essentially similar. The Russians want to sell, and global refiners want to buy, Russian crude at market prices. The Embargo and Price Cap are intended to prevent such transactions. Neither has succeeded. The Embargo has led to a simple restructuring of oil trade flows, with India, China and Turkey replacing Europe as Russia's primary export market. Similarly, the Price Cap has motivated Russia to circumvent such controls, for example, by the establishment of its own 'shadow fleet' of tankers and fraudulent declarations by market participants regarding agreed oil prices. This was entirely predictable, as enforcement-based approaches fail almost without exception, regardless of the product, country or historical period.
The US does, however, have three examples of success in ending black markets: the repeal of Prohibition for alcohol; the legalization of gambling; and the partial and halting legalization of marijuana. This is not the place to dwell on particulars, but the graph below illustrates the potential of the legalize-and-tax approach. In Fiscal Year 2023, border apprehensions of illegal immigrants were running six times the level of the Obama administration, and Border Patrol seizures of hard drugs like cocaine, heroin and fentanyl were twice their Obama-era level. By contrast, Border Patrol seizures of marijuana at the southwest border are running at 1.8% -- that's right, 1/55th -- of the level of the Obama administration. Smuggling of cannabis over the Mexican border has all but ended, and in fact, today the US is a net smuggler of marijuana into Mexico by value. That's the power of the legalize-and-tax approach, and we can use it to both close the border to illegal immigration and reform the Price Cap.

If the Speaker and the Republican conference are looking for alternatives, a legalize-and-tax approach can work for both border control and Ukraine funding.
The Republicans can require the Biden administration to begin a formal assessment of a legalize-and-tax approach to border control. This would avoid creating an obstacle to passage of a Continuing Resolution while initiating the first, crucial step towards ending illegal immigration using the proven, textbook approach. President Biden can agree to such a proposal, for it would help his re-election prospects as well. I would note that the legalize-and-tax approach to end illegal immigration has been endorsed by the Washington Examiner and received constructive support from the likes of Breitbart and the Epoch Times. The hard right is willing to take a look, and that should provide some comfort to Republicans as they consider options.
Meanwhile, Republican requirements for oversight of Ukraine spending are far too modest. The principal goal should not be Ukrainian accountability (although this is desirable), but rather making the Russians pay for the war, and not only the war, but Ukraine's reconstruction and the full spectrum costs incurred by the US and Ukraine's allies for the conflict. It's not about ensuring US taxpayer money is well spent; it's about making sure the taxpayers get their money back.
General George Patton, America's most prominent general of World War II, once famously declared, "No bastard ever won a war by dying for his country. He won it by making the other poor dumb bastard die for his country." A legalize-and-tax approach can make the other poor dumb bastard pay for the war. That's something Democrats and Republicans can both support.
Rigs and Spreads Nov. 11: Breakevens above $90!
The breakeven to add US horizontal oil rigs now exceeds $90 / barrel WTI. At $90 WTI, we can expect US operators to be cutting rigs. That is incredible by the standards of the last decade. What nostalgia one can have for the go-go days of $30 breakevens!
Rig counts
Total oil rig counts: -2 to 494
Horizontal oil rig counts: +3 to 446
The Permian horizontal oil rig count: +2
The Canadian horizontal oil rig count saw progress this week, +3 to 123, but now 5 below this week last year
The US horizontal oil rig count is falling at a pace of -0.75 / week on a 4 wma basis.
This number has been negative for 47 of the last 49 weeks
Frac spreads fell, -2 to 268
DUC inventory, as measured in days of turnover, rose modestly to 13.9 weeks
The Brent Spread (Brent – WTI) remains open, suggesting US shale oil production is exceeding expectations.
Kyiv’s PR Strategy Running out of Steam
Russia Oil Production

Ruble +8% on US dollar, Ukraine support eroding
Let's start with Price Cap metrics.
Brent and the Urals price had a ho-hum week, without material movement in either price. Brent closed the week at $85 / barrel, and Urals at $74. A wilting Brent is signaling weakness in the global economic outlook, but this happens from time to time without a broader downturn. But not always.

The Urals discount -- the difference between Russia's western crude oil export price and Brent -- continues to narrow, averaging $13.49 for the week and tightening by about $1 / barrel over the last month. Based on recent trends, expect the Urals discount to continue to decline by around $0.04 / day.
The ESPO discount -- the difference between Russia's eastern oil export price and Brent -- also continues to narrow, now under $5 / barrel. The ESPO discount may be expected to disappear entirely during the first quarter of next year.

Bloomberg reports that Russia's seaborne crude exports averaged 3.7 mbpd last week, higher than the pre-war level and inconsistent with Russian promises to cut production. Nevertheless, according to Reuters, Russia's energy ministry said on Friday that crude oil and petroleum products exports collectively are slated to fall in November by more than 300,000 barrels per day (bpd), compared to the average level in May-June.

This past week, Russia's central bank hiked a key interest rate to 15%, up from 13%. The bank blamed higher-than-expected inflation. Readers will recall that I indicated increases in Russia's money supply were consistent with 20% inflation. Easy money appears to be propagating through the system, hence the rise in inflation. The Bank has stated that it is anticipating 7% inflation for 2023. This seems implausible. Russia's central bank probably uses some version of the Taylor Rule, which would imply inflation in the 12-14% range for a 15% interest rate. At a guess, Russia's true inflation rate is twice the figure claimed by the central bank.

Ordinarily, high inflation should lead to currency devaluation, but in fact, the ruble has appreciated by 8% on the US dollar in just the last few weeks. This is in part due to rising Russian interest rates, but also attributable to the collapse of the Price Cap and Russia's blended oil export price holding near $80 / barrel. Thus, Russia faces disparate trends, with elevated domestic inflation contrasting with substantially improving terms of trade internationally. I had stated earlier that I thought late summer hype about a collapsing ruble was likely overstated, and so it proved. Should Brent resume its rise, expect the ruble to appreciate further.

Finally, a newly released Gallup poll shows ebbing support for Ukraine in the US. A majority still supports Ukraine, but clearly, disappointment with a lack of material progress during the summer campaign has taken the wind out of the public's sails. Kyiv needs a rethink on financial and messaging strategy, and right now, the surreal passivity of the Ukrainian bureaucracy and Zelenskyy's inner circle is impeding action on these fronts.

Rigs and Spreads Nov. 3: The light in the tunnel was a train after all
After three weeks of modest gains, rig counts have resumed their decline, giving back all their gains in just this past week
Rig counts
Total oil rig counts: -8 to 496
Horizontal oil rig counts: -8 to 443
The Permian horizontal oil rig count: -4
The Canadian horizontal oil rig count saw progress this week, +1 to 120, but still is 16 below this week last year
The US horizontal oil rig count is falling at a pace of -0.5 / week on a 4 wma basis.
This number has been negative for 46 of the last 48 weeks
Frac spreads fell, -5 to 270
As last week, there is a stark mismatch between rigs and spreads, with DUC inventory, as measured in days of turnover, falling to a nine-year low of 13.6 weeks
The rig / spread relationship remains highly unstable
To attain stability in the DUC count, rigs must either rise by 83 or spreads must fall by 42.
Given that rig counts are falling at an implied WTI price above $90 / barrel, a rapid roll-off of spreads seems likely at some point
Interestingly, the Brent Spread (Brent – WTI) opened back up to $4+ / barrel in the last two weeks
An open spread has implied US production growing faster than Brent zone production, compelling US operators to offer a modest discount to place incremental barrels in the market
Historically, this spread is associated with US production growth around 400 – 600 kbpd / year
If that remains true, then EIA pessimism on US short-term C+C growth is misplaced
Rigs and Spreads Oct. 27: A Clear Trough
A clear trough has emerged, and rig counts are rising, if slowly
Rig counts
Total oil rig counts: +2 to 504
Horizontal oil rig counts: +2 to 451
The Permian horizontal oil rig count: +2
The Canadian horizontal oil rig count saw progress this week, +1 to 119, but still 19 below this week last year
The US horizontal oil rig count is rising at a pace of +1.0 / week on a 4 wma basis.
This number is positive for the first time in 48 weeks
Frac spreads rose, +6 to 275
Even more than last week, there is a stark mismatch between rigs and spreads now, with DUC inventory, as measured in days of turnovers, falling to a nine-year low of 13.9 weeks
The rig/spread relationship is even more unstable than I noted last week. To attain stability in the DUC count, rigs must either rise by 84 or spreads must fall by 43.
If the breakeven to add rigs of $83 holds, then we should see appreciable rig additions in the coming weeks.
On the other hand, if rig counts fail to show material signs of life (cc +4 hz rigs per week), then we may be seeing the last hurrah of the US shale sector, with operators running down DUC inventories like an alcoholic taking a last drink before entering rehab.
Rigs and Spreads Oct. 20: Reaching a bottom?
Rigs counts once again saw a glimmer of hope this week.
Rig counts
Total oil rig counts: +1 to 502
Horizontal oil rig counts: +0 to 449
The Permian horizontal oil rig count: +1
The Canadian horizontal oil rig count saw a solid progress this week, +4 to 118, but is still 17 below this week last year
The US horizontal oil rig count is falling at a pace of -0.5 / week on a 4 wma basis.
This number has been negative for 46 of the last 47 weeks
If the rig count change is zero or higher next week, then the 4 wma change in rig counts will turn positive for the first time in 11 months
Frac spreads rose, +6 to 269
There is a stark mismatch between rigs and spreads now, with DUC inventory, as measured in days of turnovers, falling to 14.3 weeks. This the lowest since the early days of the shale revolution
The rig/spread relationship is now clearly unstable
To attain stability in the DUC count, rigs must either rise by 75 or spreads must fall by 38. This is the most distorted this number has been since the height of the pandemic.
If the breakeven to add rigs of $83 holds, then we should see appreciable rig additions in the coming weeks.
On the other hand, we have only two weeks of positive data on rigs, which could easily prove a false dawn. If that’s the case, then at some point, spreads will start to fall off dramatically
The EIA issued the October DPR this past week
In the October report, September crude and condensate production from key shale plays fell to 9.47 mbpd, down 34 kbpd from August.
However, total August C+C shale production was revised up a whopping 237 kbpd, and the May-August period was revised up by an eye-popping 182 kbpd on average
Having said that, revisions have been so large lately that my confidence in reported numbers is at a low at present.
As I noted last week, the EIA has been on a revision spree lately – which happens sometimes – but it does make the data hard to interpret, and reliable month-to-month comparability may not be restored until early next year.
Urals rebounds; renewed emphasis on Cap enforcement; Gaza partition
Oil Prices
Brent was choppy last week, partially recovering from the prior week's sell-off. At writing, Brent was trading at $90 / barrel. The Biden administration, as reported by Reuters, announced sanctions on owners of tankers carrying Russian oil priced above the G7's price cap of $60 a barrel, one in Turkey and one in the United Arab Emirates. Brent promptly soared by $5 / barrel.
Urals is holding near $76, $16 above the Cap. ESPO, Russia's principal eastern oil export price, was last reported at $86.

The Urals discount, the difference between Russia's western crude oil export price and Brent, opened back up to $14, as we had expected.

The EIA reports Russian oil production for September largely unchanged around 10.5 mbpd, 0.8 mbpd lower than its pre-war level. No further declines are expected.
S&P Global estimates that Russia's seaborne crude oil exports are largely unchanged since the start of the war, and up a bit in September. China and India remain key buyers.

Source: Commodity Insights
S&P Global has also made estimates of Russia's seaborne crude exports by type of carrier and pricing regime. The results are somewhat surprising. Only 57% of Russia' seaborn crude exports fall into the Urals pricing zone. A hefty 43% of exports are to the east and, to appearances, not subject to the Price Cap, whether carried on western or non-western tankers. Of Russia's western Urals trade, only 54% is carried on western tankers, that is, those subject to the Price Cap. Overall, only 31% of Russia's seaborne crude trade is both subject to the Urals price and carried by western tankers. That is, only one-third of Russia's seaborne crude exports are subject to the Price Cap, although this expands to 45% if all eastern trade carried by western tankers, is included.

Source: Commodity Insights
At this point, therefore, we can claim that the Price Cap mechanism is riddled with holes, even assuming that the Price Cap were enforced and effective on the Urals trade carried on western tankers. Readers know that I have been harshly critical of the Price Cap, even months before it was implemented. We now have an additional reason: the Biden administration's analytics (including those of the Fed and Treasury) were weak. This, coupled with a technically deficient structuring of the Cap, has led to enforcement better described as nominal than substantive.
Hamas, Israel, and the Partition of Gaza
The majority of Ukraine watchers have weighed in on events in Gaza. I will take similar liberties.
The press and media commentators continue to refer to Hamas militants as terrorists, and certainly, the description is apt. Nevertheless, an invasion of 1,000 Hamas fighters killing more than one thousand Israelis is not a terrorist act. It is an act of war. The term 'terrorist' creates the impression that Hamas fighters were somehow an extremist, splinter group, acting without the approval or support of Gaza's government and against the will of Gaza's population. This is untrue. The attack was planned by Hamas and justified by its military chief, Mohammed Deif, as a response to "Zionist colonial occupation". The assault on Israel was a policy decision of and implemented by the government of the Gaza Strip.
The degree of public support in Gaza is a more nuanced question. Hamas won Palestinian elections in January 2006, and no open elections for the government of the Gaza Strip have been held since. Hamas remains in charge. Palestinian opinion polling from this past summer suggests that Hamas would have won an election there prior to the attack on Israel. Nevertheless, a Washington Institute poll from July 2023 concludes that, while a "majority of Gazans (65%) did think it likely that there would be “a large military conflict between Israel and Hamas in Gaza” this year, a similar percentage (62%) supported Hamas maintaining a ceasefire with Israel." Did the Palestinians in Gaza support the attack on Israel? Condemnation by Palestinians of the attack on Israel has been muted to non-existent. The polling data suggests that many Gazans support violent confrontation, but perhaps not a majority. Reuters reports that US Secretary of State Blinken said he knew that Hamas did not represent the Palestinian people or their legitimate aspirations. The polls say otherwise.
A terrorist act that kills a dozen victims will prompt a limited response, for example, the targeting of leadership with precision airstrikes or commando raids to free hostages. The murder of one thousand civilians falls into an entirely different category. The US treated the 9/11 attacks, which killed 3,000, as acts of war and invaded and conquered two countries as a result. The 1,400 Israeli victims would represent nearly 50,000 deaths in the US, adjusted for population. Like the US after 9/11, Israel will treat the recent attacks as acts of war by the government and people of Gaza, not merely one-off acts of terrorism by lone-wolf extremists.
Unlike the US, which invaded Afghanistan and Iraq purely as disciplinary measures without the intent to take land, Israel will take land over punishment. Israel cannot invade the Gaza Strip and govern it as the US did Iraq and Afghanistan. In Gaza's dense, urban environment, the risks and complications are unpalatable. Instead, both opportunity and necessity drive Israel to take territory. By attacking Israel on such a large scale, Hamas has opened the door for Israel to seize land which conservative Israelis consider organic to greater Israel. Such an opportunity may occur only once or twice in a century, and it may not be wasted. Further, Israel's failure to detect and counteract the Hamas incursion represents a catastrophic failure of leadership. By any reasonable measure, Prime Minister Benjamin Netanyahu's career should be finished. His only saving grace could be the annexation of a substantial portion of the Gaza Strip. This would make fallen Israelis not victims, but soldiers and martyrs whose blood has secured Israel's historic lands. It may just redeem the Prime Minister's reputation. As a political necessity, therefore, Netanyahu must seize part of Gaza.
Plans are being implemented. The first step is to clear north Gaza, including Gaza City, of its Palestinian inhabitants. The expulsion of the local population is well underway. Further, every edifice in north Gaza will likely be razed to prevent talk of return, ever. This, too, is already in process. Finally, a new border must be designated, and one has been: the Besor Stream in the Wadi Gaza, about halfway down the Strip. If north Gaza is cleared of its Palestinian population, its structures destroyed and the rubble cleared; and if only Israeli Defense Forces remain beyond the wall to be constructed north of the Wadi Gaza Reserve, then Israel will have annexed half of Gaza as a practical matter.

Source: ABC News
One can only wonder at the sheer stupidity of Hamas. Their plans for the first day of the war are clear. What did they expect on Day 2? Did they think that killing 1,400 Israelis would be a freebie? Had they no notion that such an act of war would prompt Israel to seize land? Whatever they were thinking, the reality will likely be the loss of half of the Gaza Strip to the State of Israel.
For just this reason, President Biden would do well to refrain from visiting Israel just now. If the Hamas attack on Israel resembles 9/11, the Israeli response will constitute another Nakba (catastrophe), the destruction of the Palestinian society and homeland in 1948, and the permanent displacement of a majority of the Palestinian Arabs. The seizure of north Gaza by the Israelis will pass into the Palestinian and Arab narrative of historical victimhood as yet another act of merciless aggression by Israel, and so it will be. Nevertheless, the attack on Israel creates both the opportunity and necessity. President Biden's presence there will imply US endorsement of what is to come and may stain America's reputation for decades. The President should stay away from Israel until the worst has passed.
Rigs and Spreads Oct. 13: Best week for rigs since last November
Rigs and Spreads
Rigs counts saw their best week since last November
Total oil rig counts: +4 to 501
Horizontal oil rig counts: +4 to 449
The Permian horizontal oil rig count: +1
The Canadian horizontal oil rig count saw a bit of life this week, +8 to 114, but still 26 below this week last year
The US horizontal oil rig count is falling at a pace of -2.5 / week on a 4 wma basis.
This number has been negative for 45 of the last 46 weeks
Frac spreads rose, +3 to 263
As earlier, this is still too high for the current rig count, as DUCs continue to fall.
To hold DUCs steady, the spread count must fall by 27
US Crude and Condensate Production Revisions
The most interesting news this week was EIA revisions to US crude and condensate production.in both the monthly STEO and weekly PSR
US crude and condensate (C+C) production has been revised up 400 kbpd in the October STEO.
This changes the production narrative, as it shows almost unbroken growth from Jan. 2022 to Sept. 2023, with growth averaging about 1 mbpd / year despite falling rigs counts since last December

Since August 2022, a gap had appeared between US C+C production as reported in the weekly PSR and the monthly STEO (bottom graph).
As a result of this gap and the upward revision per the monthly STEO, the weekly C+C numbers have been revised up 1 mbpd in the last two months, bringing the PSR and STEO C+C numbers back into alignment (red circle, graph below)
This is a very large revision, but sometimes that's how it goes. It does make the data harder to interpret.

The latest STEO (top graph) also shows US C+C production peaking last month.
Given the strength of trend to that point, a near term decline would seem less likely
Therefore, an upward revision of Q4 C+C numbers seems quite plausible
On the whole, however, the EIA sees US production peaking, which seems probable given on-going declines in rig counts, but timing is uncertain.
Rigs and Spreads Oct. 6: The Permian leads down
The Permian led rig declines this week.
Rig counts
Total oil rig counts: -5 to 497
Horizontal oil rig counts: -2 to 445
The Permian horizontal oil rig count: -2
The Canadian horizontal oil rig count had a bad week, down 8 to 106 and 33 below last year for the week
The US horizontal oil rig count is falling at a pace of -3.5 / week on a 4 wma basis.
This number has been negative for 44 of the last 45 weeks
Frac spreads rose, +5 to 260
As earlier, this is still too high for the current rig count, as DUCs continue to fall.
To hold DUCs steady, the spread count must fall by 26
Exxon is reportedly making an offer for shale leader Pioneer
The absorption of Pioneer into an established player like Exxon would once again mark the end of the shale revolution
Urals to $70, Ruble to 100 in Market Panic
Oil markets saw a big sell-off this past week. Brent dropped by nearly $10 / barrel on high interest rates and Wednesday's Department of Energy (EIA) report showing US gasoline consumption collapsing, leading to a panic over the possibility of a global recession. Pencil one in, but probably not yet. US employment remains strong, and both diesel and jet fuel demand in the US are robust. Oil prices merited a reset after nearly three months of secular gains, and while they may retreat a bit more from current levels, Brent and Urals should begin to climb again as sentiment stabilizes.
For the moment, however, Russian oil prices have followed Brent down with a $10 / barrel decline. We estimate Urals closed the week around $70, with hard data available only through Wednesday.

The Urals discount narrowed this week to under $12 / barrel, but the number is probably an artefact resulting from delays in reporting Russian oil prices. Figure a $14 - $16 / barrel discount re-emerging when Brent stabilizes.

The ruble once again fell to more than 100 / USD, closing the week at 100.4 rubles / USD. Investors typically flee to the US dollar during panics, and therefore one should avoid reading too much into the current ruble exchange rate. Assuming capital markets regain their composure, the ruble might crawl back to the 96-98 / USD range over the next week or so.

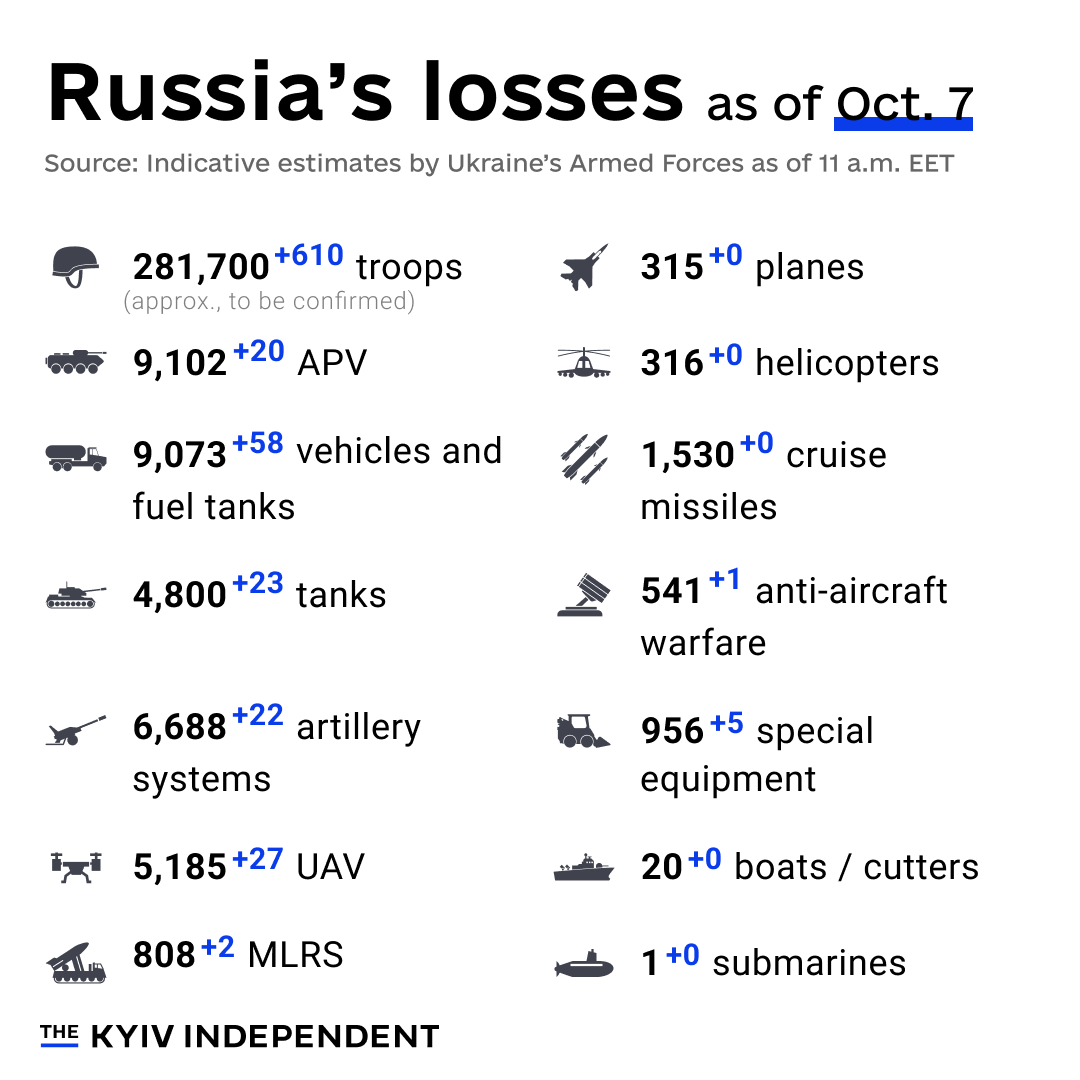
Overall, the week was marked by panic in markets and chaos in the US Congress, prompting fears of funding gaps for Ukraine. I will refrain from lecturing about funding shortfalls and the Price Cap this week. Instead, I refer my readers to the pace at which Ukrainians are destroying Russian equipment. Assuming Ukraine Defense Ministry numbers are broadly accurate, the Ukrainians are eliminating Russian equipment on an industrial scale with manufacturing-line routine. Today's numbers are all but spectacular and not too far removed from those of the last several months.
Urals breaks $80; failed Price Cap funds surge in Russian war spending
As expected, Urals broke through the $80 barrier, closing on Friday at $80.21. Brent ended the week at $92, with the US benchmark WTI at $91. This is the closest WTI has been to Brent in some time and likely signals the end of the shale revolution.
Brent has risen by $22 / barrel in the last three months. We last saw such surges in 2008 before the Great Recession and 2011, leading the EU into a brutal, near two-year recession. A replay is likely this time as well, but oil prices need to move significantly higher before the economy craters. The pace of the rise in Brent suggests further increases are likely. Pencil in another $10-20 / barrel in the next, say, 90 days. This would put Brent in the $100-$110 per barrel around year-end.

Unsurprisingly, the Urals discount -- the difference between the Urals and Brent oil prices -- compressed last week to just under $14 / barrel, almost the smallest since the start of the war and consistent with the tendency of the spread to contract when Brent is strong. The ESPO discount -- the difference between Russia's Pacific oil price and Brent -- similarly continues to compress, much as we have been forecasting. ESPO is holding around $90 / barrel.

The Urals oil price is near an eight year high and $17 higher than its level year ago, before the implementation of the Price Cap. If we allow Brent at $100 - $110 at year end, that would peg Urals in the $86-$98 range heading into 2024.

Oil and the War
Russia is looking at a massive increase in defense spending. The Moscow Times reports that Russia's Finance Ministry projects defense spending “to jump by over 68% year-on-year to almost 10.8 trillion rubles ($111.15 billion), totaling around 6% of GDP — more than spending allocated for social policy." The Kremlin has limited resources to fund this increase. Tax increases, spending cuts and international borrowing look dicey. Therefore, Moscow is left with the alternatives of bluffing, printing money, or increasing oil revenues. The Russian central bank does not typically bluff. Therefore, Moscow is counting on increasing oil revenues to bankroll the war in Ukraine.
This comes as no surprise for those who follow my macro oil forecasts and is the direct result of a poorly designed and failing Price Cap. For example, in February, I noted in The Oil Supply Outlook (and why it matters for Ukraine) that
The conditions are present for a material tightening of the market in the medium to long term. After 2023, oil price trends favor Russia, and perhaps substantially so. For Ukraine, this could pose a serious threat, as the current European and US sanctions on Russian oil are unsuitable to deal with such an eventuality.
This is belatedly beginning to dawn on the Biden administration. Even two weeks ago, various Biden administration proxies were defending the Price Cap in its current form (Benjamin Harris here and Eric Van Nostrand here). This past week, however, the tone has turned more somber. Bloomberg notes that "Treasury Secretary Janet Yellen said that recent market prices for Russian oil suggest that the Group of Seven’s price cap is no longer working as hoped, her first such public acknowledgment of challenges with the program." Some analysts go farther. Julian Lee, Bloomberg's oil markets analyst, in a Washington Post op-ed, It’s Time to Scrap the Russian Oil Price Cap, writes
It gives me no pleasure to say this, but it’s time to scrap the Russian oil price cap.
Lee is a solid, level-headed analyst. But in this case, his advice would be disastrous. I would not be surprised to see Brent hovering around $110 / barrel much of next year. If we allow that every $25 barrel above $55 on a Urals basis allows Russia to double its military spending, then $110 Urals would allow Russia to triple its military budget compared to the pre-war era. This is not only inadvisable, it's absolute insanity.
The reality, unfortunately, is that the Biden administration has not a clue how to fix the Price Cap. None of the administration, Treasury or Fed has the appropriate skill mix, which requires oil markets experience (supply and demand forecasting); oil price forecasting; an understanding of the linkage of oil prices to the economy, politics and society; crude and refined products shipping and pipelines expertise; a solid understanding of black market theory (my unique specialty); and familiarity with the eastern Europe mindset and culture. None of this appears on, for example, the above-mentioned Benjamin Harris's otherwise impressive CV.
The rather unpleasant implication is that Julian Lee's vision, whether de facto or de jure, is likely to be realized: the Price Cap will be scrapped. My Ukrainian readers should contemplate whether this is a desirable outcome, or whether Kyiv might finally wish to take a stand on the matter.
Ukraine's Emerging Funding Challenges
This is even more acute as Ukraine is running up against funding resistance. This comes as no surprise once again, and for more than a year I have been warning about using the US Federal budget as a bottomless piggy bank. To the average American, Ukraine is every bit as exotic and remote as Papua New Guinea, Yemen or Andorra. Why are we spending so much money on that distant place? Is it really our fight? Many, many Americans are asking these questions.
The situation will deteriorate from here. Part of it is simple war fatigue from the funders' side. More importantly, we appear to be heading toward another oil shock, with JP Morgan forecasting a 7 mbpd shortfall in the oil supply by 2030, which is enormous. As oil prices break through $100, $110, or $120, the Russians will feel emboldened and Ukraine's western allies will find themselves enfeebled politically and economically, and they will progressively reduce their exposure to Ukraine. Recent Congressional theatrics and the Slovakian elections can probably be finessed. But they are a clear warning shot and a harbinger of things to come.
The bottom line is this: The Price Cap can and should be appropriately restructured. This would transform the war into a profit center for the US, with about $10 bn in US government annual support to Ukraine offset by about $25 bn in revenues to our defense industry. That would silence Ukraine's critics and ensure Kyiv has plenty of money for both the conflict and reconstruction.
Rigs and Spreads Sept. 29: More of the same
More of the same. Rigs and spreads continue to fall, high oil prices notwithstanding.
Rig counts
Total oil rig counts: -5 to 502
Horizontal oil rig counts: -4 to 447
The Permian horizontal oil rig count: -4, again
The Canadian horizontal oil rig count remains essentially unchanged over the last four months, this week down 23 from last year
The US horizontal oil rig count is falling at a pace of -4.0 / week on a 4 wma basis.
This number has been negative for 43 of the last 44 weeks
Frac spreads fell, -4 to 255
This is still too high for the current rig count, as DUCs continue to fall.
To hold DUCs steady, the spread count must fall by 20
It looks like the industry has settled on 16 weeks of DUC inventory, where it stood on Friday, as the new normal.
As a result, expect spreads to roll off pro rata with rigs from here on out -- beyond the 20-spread readjustment necessary to hold DUCs steady -- at a ratio of one spread for every two rigs.

The Brent Spread – the difference between WTI and Brent – is also signaling the end of the shale revolution
Historically, WTI sold at a premium to Brent
Since the shale revolution, WTI has typically sold at a discount to Brent, generally in the range of $4 / barrel in recent times.
This discount was necessary to place incremental US shale oil barrels in the market.
In the last two weeks, the Brent spread has collapsed to around $1.50 / barrel, suggesting a tightening US market, which could be explained by low or no growth in US shale oil production.
Once again, nothing cheery in the data
Rigs and Spreads Sept. 22: Peak Shale?
This week’s numbers were all but disastrous. Both rig counts and shale oil output continue to fall
Rig counts
Total oil rig counts:-8 to 507
Horizontal oil rig counts: -8 to 451
The Permian horizontal oil rig count: -4
The Canadian horizontal oil rig count continues to lag, down 28 from last year.
The US horizontal oil rig count is falling at a pace of -3.0 / week on a 4 wma basis.
This number has been negative for 42 of the last 43 weeks
Frac spreads fell, -5 to 259 This is still too high for the current rig count, as DUCs continue to fall.
DUC inventory has fallen back to 15.7 weeks of turnover
The EIA’s latest DPR, published this past week, also shows shale oil output from the key plays declining, down 17 kbpd from July. In addition, the EIA is forecasting further declines, with October shale oil output down 82 kbpd from the July peak. That is, given the continued decline in rig counts, the EIA appears to be calling peak shale oil production for July 2023.
It is important to note that the EIA routinely revises previous output figures and that EIA projections should be considered provisional, not definitive. Nevertheless, the EIA production decline forecast is consistent with the chronic erosion of rig counts we have seen since last December.
Last week, I wrote this:
Lagged oil prices for the next eight weeks are consistently above $80 WTI, and at times well into the mid-$80s. As a result, we should in theory see at least modest life in the horizontal oil rig count. If we do not, it will be further evidence that the underlying problem is a lack of drilling opportunities, not unfavorable economics
Instead of modest rig additions, we see a stiff decline of 8 horizontal oil rigs this week, half of them from the Permian.
The continued decline of rig counts, particularly with lagged WTI above $80, is bad. The decline in shale oil output from key plays is bad. And the continued erosion in the DUC inventory is also bad.
There is nothing redeeming in the data this week. Perhaps the numbers turn around at some point, but right now, the picture is ugly.
Urals heads toward $80
WTI and Brent have been rocketing up, respectively at $93 and $96 at writing. (For those interested in the oil market dynamics, see my presentation from Italy last month. I'll have a separate post on this).
Urals continues to track Brent, with Urals at writing posted at $78.12. Given the surge in Brent, we might expect to see Urals at $80 / barrel in the next week or so, $20 higher than the $60 Price Cap.
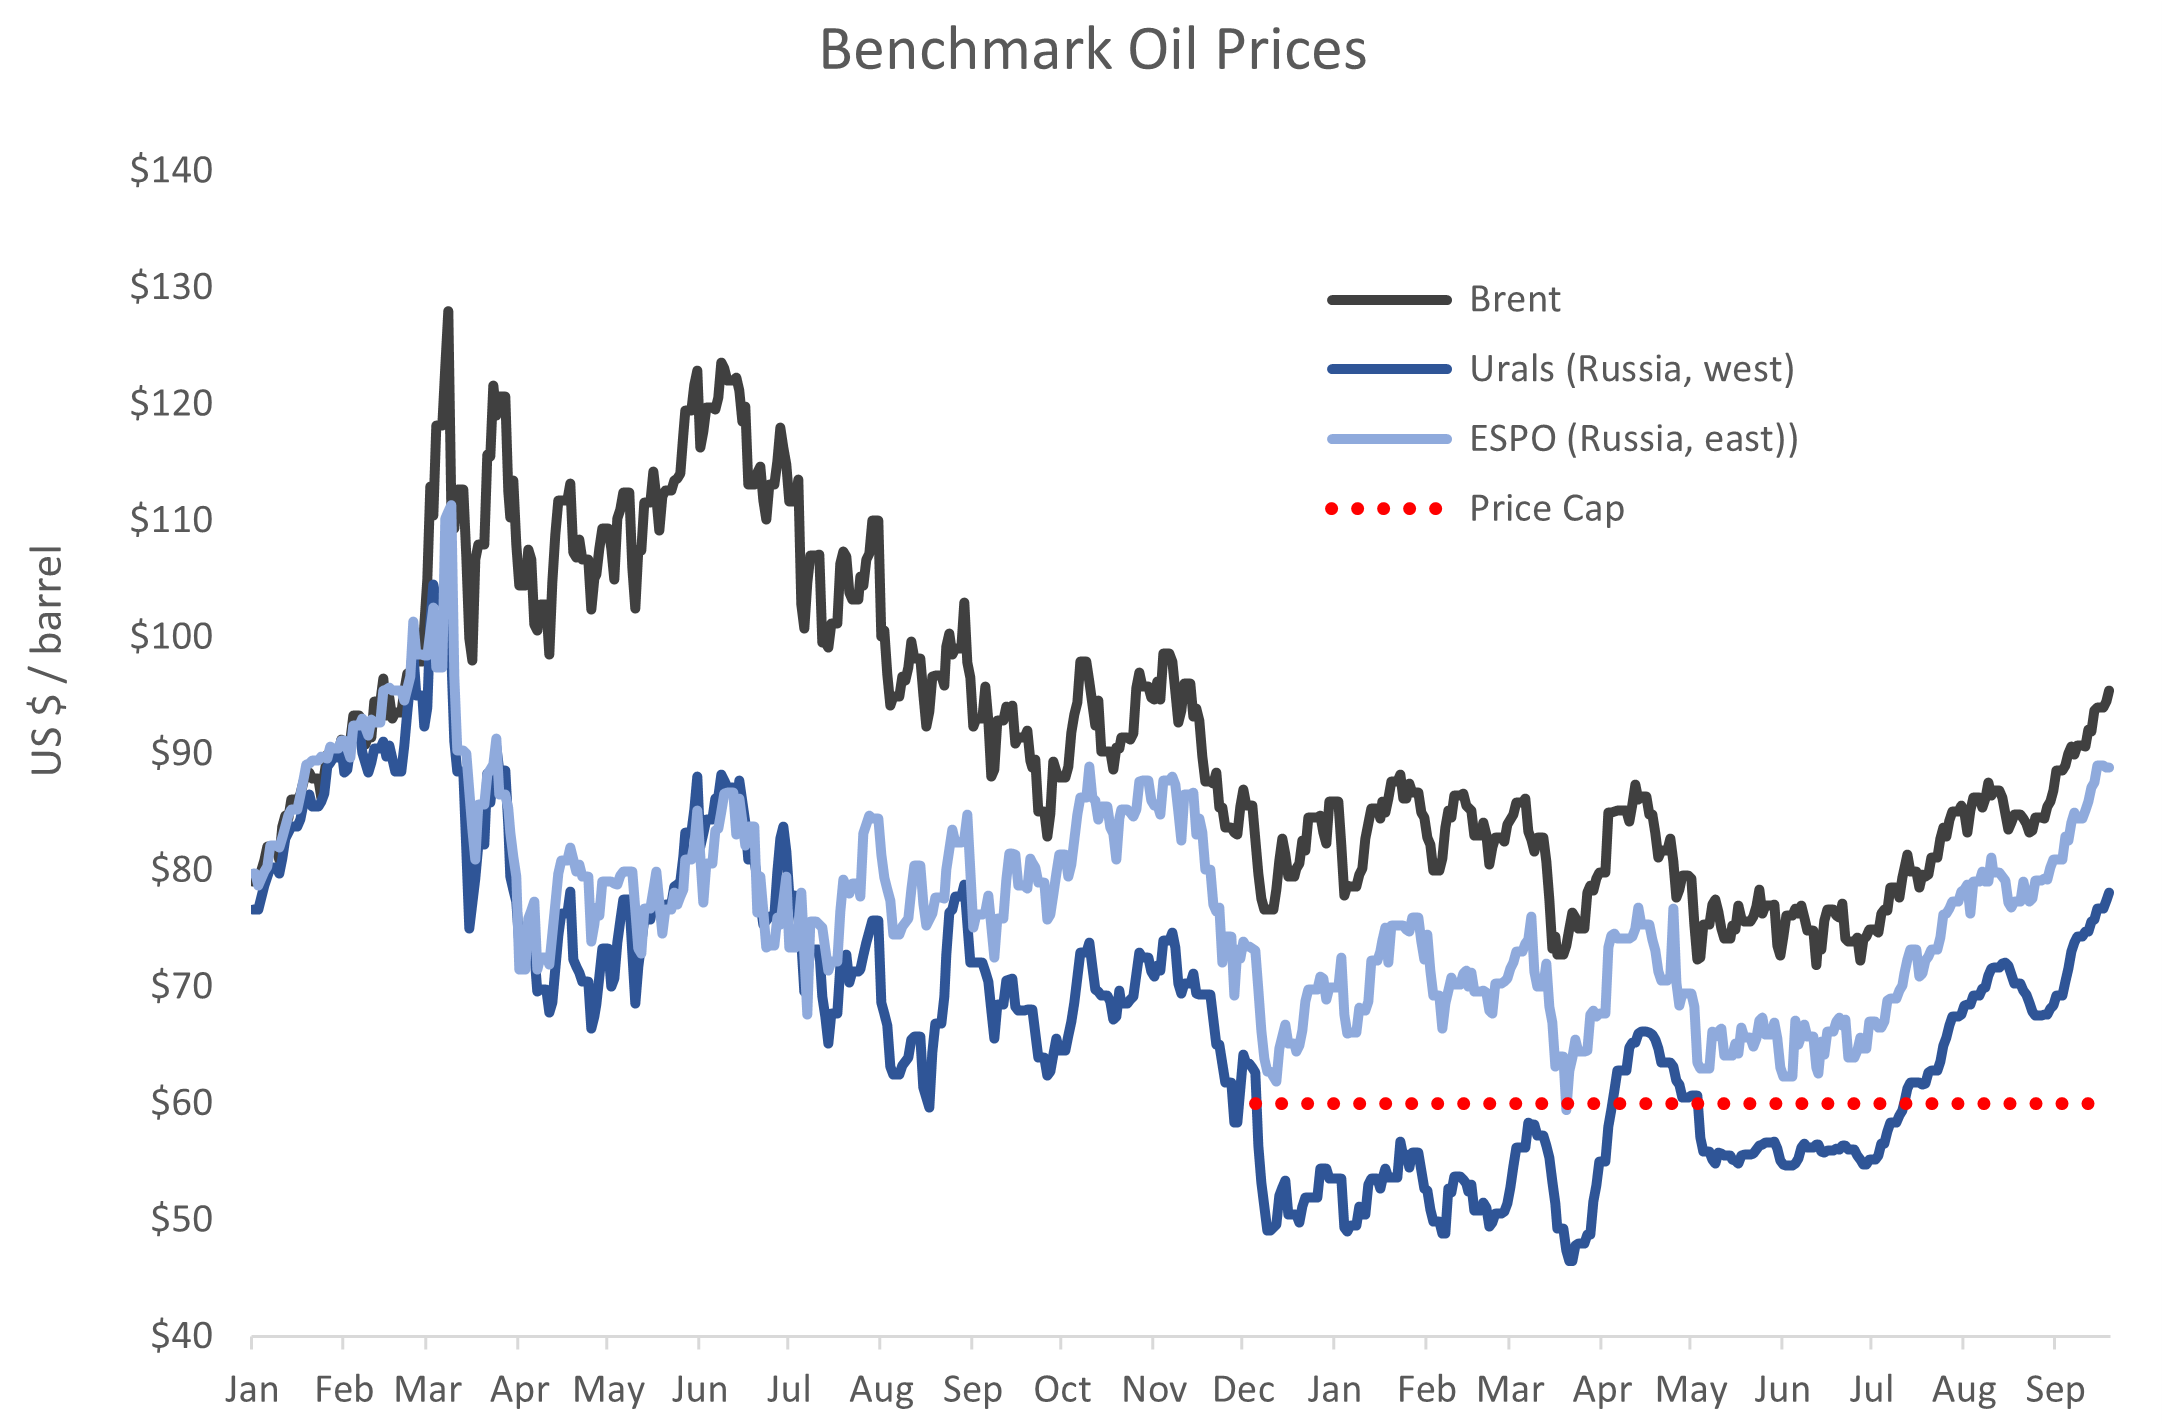
The Urals discount is largely holding steady, about $17 at writing. I expect the discount to narrow over time. The ESPO discount continues to shrink, again per expectations.
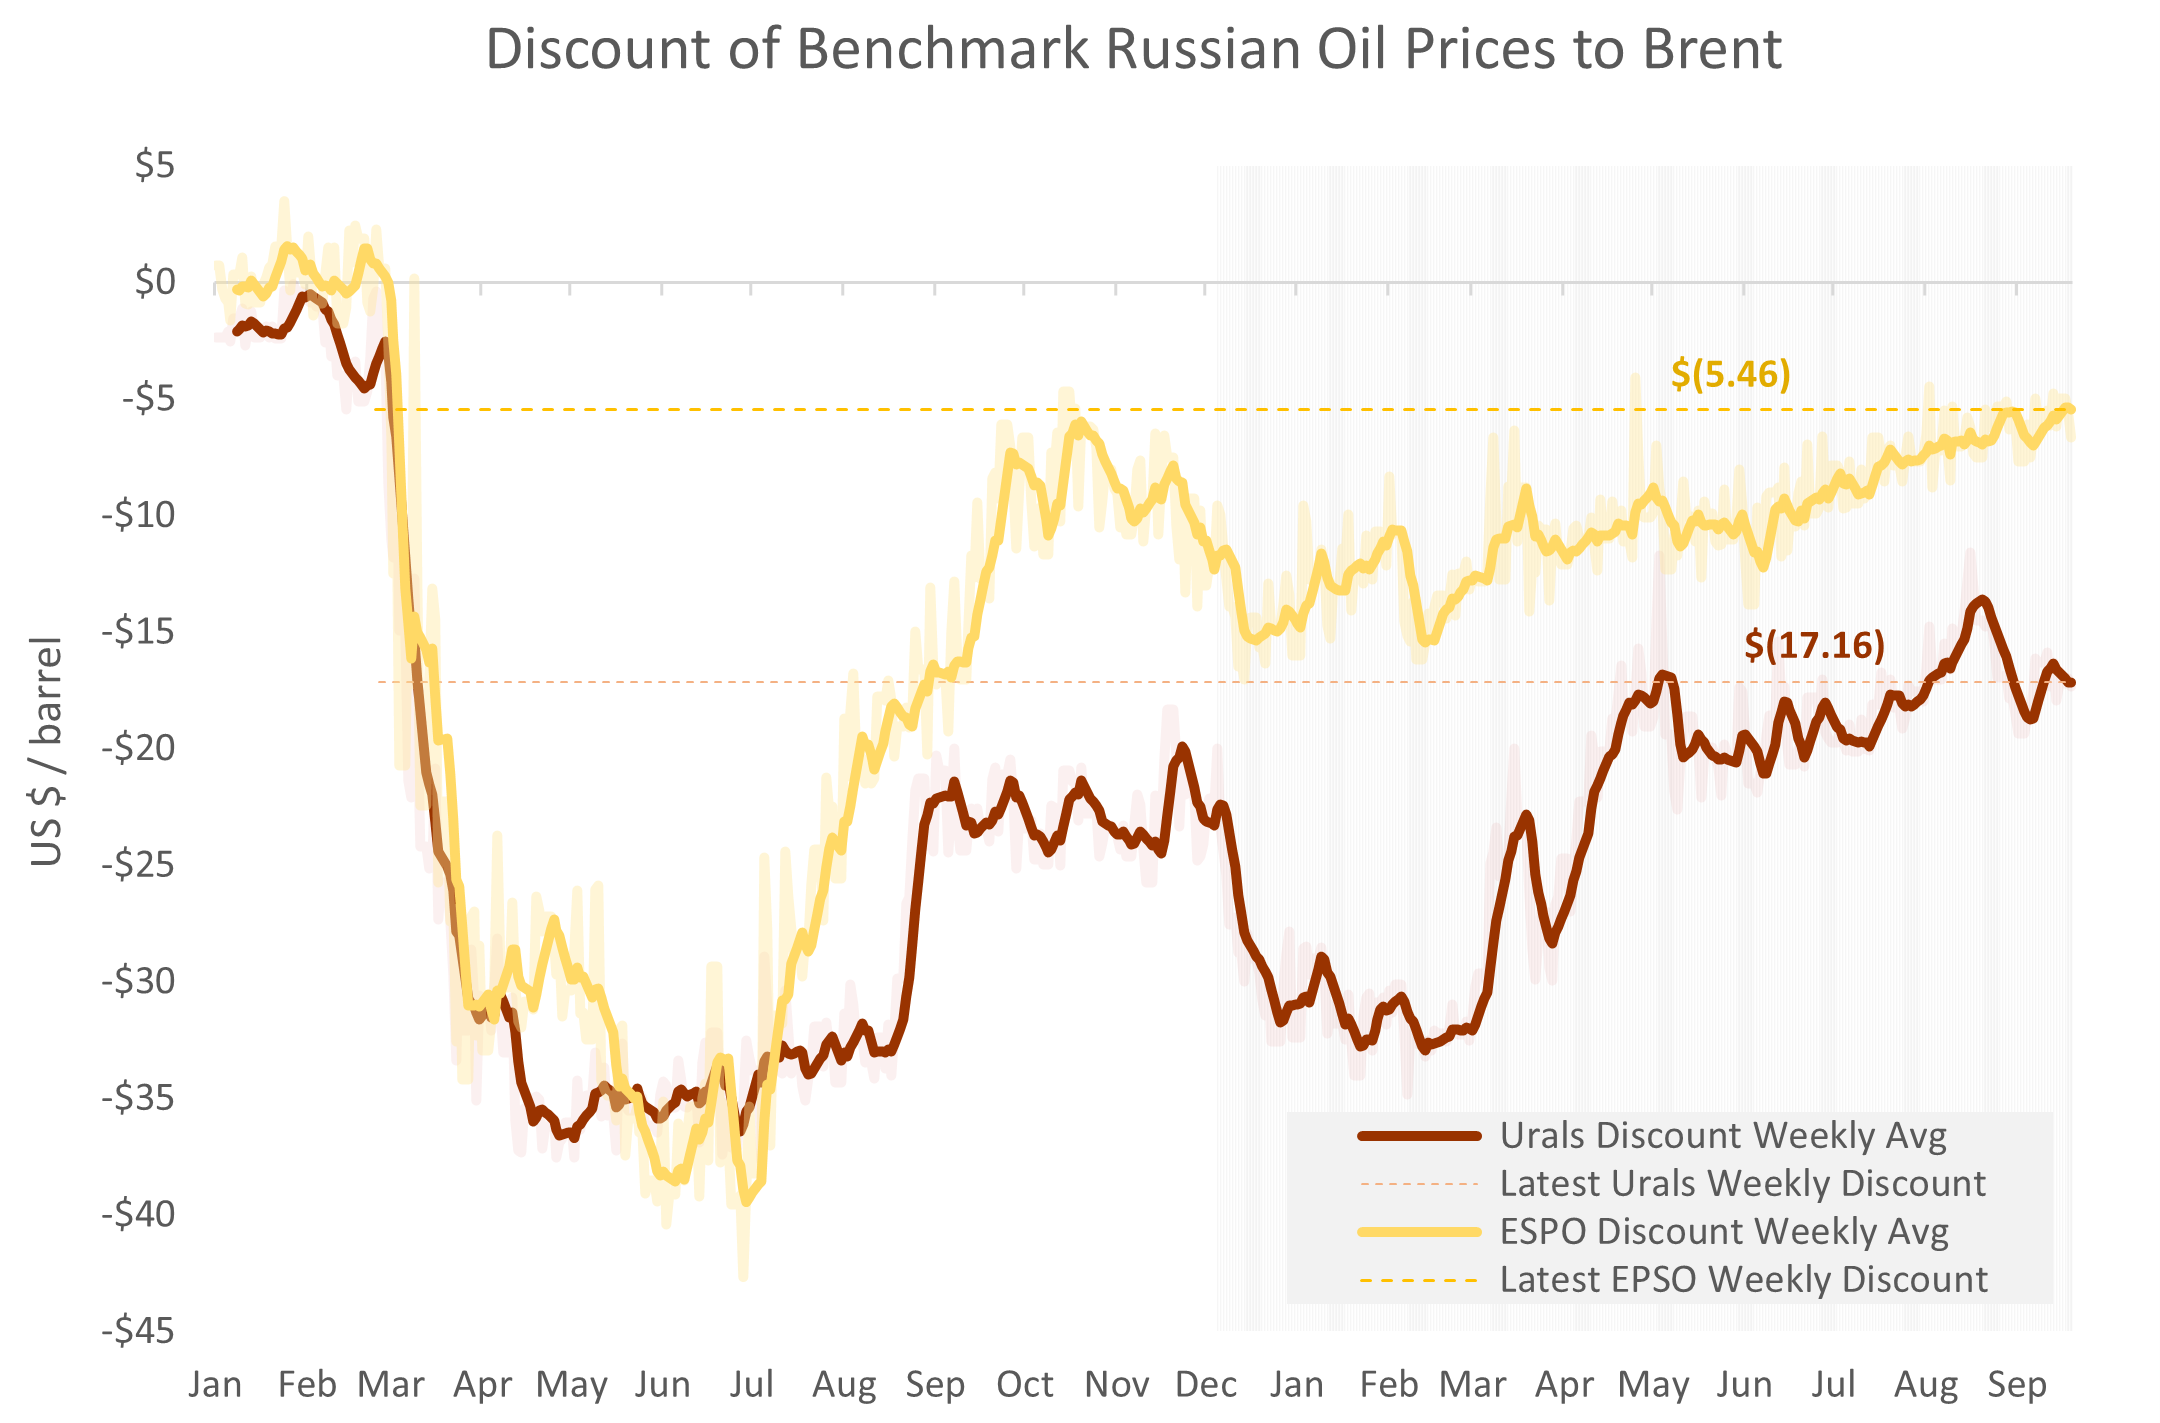
Urals is now $22 / barrel above the average for the 2015-2021 period and near a peak for the week in the last nine years. With ESPO at $89, Russia's blended crude oil export price is just about $80, sufficient to double Russia's military budget compared to the pre-war period (assuming Russia can repatriate those earnings).

The ruble continues to hold up, near 97 rubles / USD. There has been no collapse. Russia's central bank is doing its share, raising benchmark interest rates to 13%. I would note that there is no such thing as 13% interest rates in the 5-7% inflation environment Russia's central bank projects for 2023. Inflation is likely substantially higher, as I have argued, because the Kremlin is funding the war in part by printing money. With the increase in oil prices, this pressure may ease, and it is not inconceivable that the ruble will stabilize near its current range. Much depends on the evolving nature of Russian federal outlays, including for the war, as well as the portion of oil export earnings Moscow is able to repatriate.

The Biden administration's proxy at Brookings has defended the Oil Price Cap. The author, Benjamin Harris, was one of the program's architects. I am not certain his analysis is intended as a defense of the Price Cap; perhaps it is better read as a eulogy. Defending the Cap is exactly the wrong response, because surging Brent and WTI will make a mockery of the supporting arguments. Americans are not going to care a whit about rationalizations. They are going to care about pump prices, with Republican candidates pillorying the Biden administration for its incompetence in constructing the program, and justifiably so. The Price Cap needs to be fixed, not defended in its current form.
Rigs and Spreads Sept. 15: Stabilization
Horizontal oil rigs stabilized this week
Rig counts
Total oil rig counts were +2 to 515
Horizontal oil rig counts were +0 to 459
The Permian horizontal oil rig count was up 1
The Canadian horizontal oil rig count continues to lag, down 24 from last year.
The US horizontal oil rig count is falling at a pace of -2.0 / week on a 4 wma basis.
This number has been negative for 41 of the last 42 weeks
Frac spreads rose, +12 to 264. Again, this is not sustainable without rigs additions.
DUC inventory fell back to 16.4 weeks
We are approaching the moment of truth for the shale industry
For the last several months, the breakeven to add rigs has averaged around $77 WTI
At writing, WTI was $91
Lagged oil prices for the next eight weeks are consistently above $80 WTI, and at times well into the mid-$80s
As a result, we should in theory see at least modest life in the horizontal oil rig count
If we do not, it will be further evidence that the underlying problem is a lack of drilling opportunities, not unfavorable economics